Medical bills can pile up quickly after an illness, surgery, or hospital stay. Even with health insurance, you may still owe more than you can afford.
If you are struggling with medical debt in Wisconsin, you have options. You may be able to get financial help from the hospital, negotiate a lower bill, dispute incorrect charges, or use bankruptcy to clear qualifying debts.
Before you pay a bill or agree to a payment plan, take time to understand what you owe and what help may be available. Here is what you need to know.
Why Medical Bills Become Hard to Pay
Medical debt can build up for several reasons. You may have a high insurance deductible, receive care your plan doesn’t fully cover, or miss work while recovering.
You may also receive separate bills from the hospital, doctor, lab, and other providers for the same visit. Even with insurance, these costs can add up quickly.
If the balance is more than you can afford, the next step is to understand how unpaid medical bills may affect your credit and what protections are available.
How Medical Debt Can Affect Your Credit
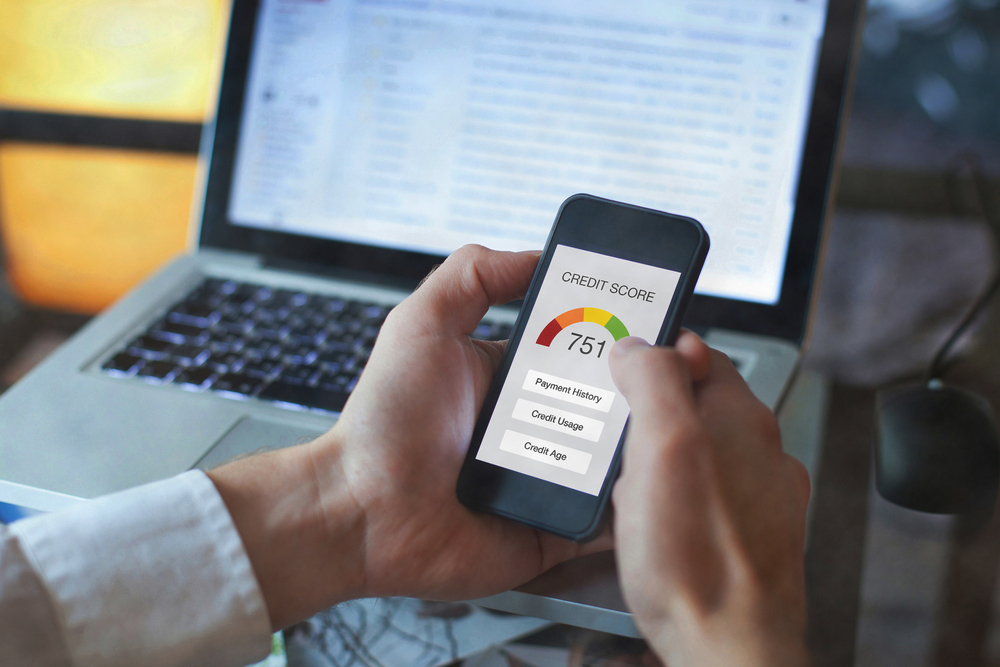
An unpaid medical bill does not always show up on your credit report. The three major credit bureaus—Equifax, Experian, and TransUnion—leave certain medical collection debts off reports.
Under current policies, they don’t report paid medical collections, medical collections with an initial reported balance under $500, or unpaid medical collections less than one year old. Other unpaid medical collections may still appear on your report and affect your credit score.
In January 2025, the federal government announced a rule that would have removed more medical debt from credit reports. The rule was overturned in July 2025, so the credit bureaus’ own policies still matter.
You can check your credit reports for free at AnnualCreditReport.com. If you find a medical debt that is incorrect or should not be listed, you can dispute it.
What Legal Protections Do You Have in Wisconsin?
Wisconsin and federal laws protect you from certain unfair collection practices and unexpected medical bills.
Debt Collection Protections
The federal Fair Debt Collection Practices Act (FDCPA) and Wisconsin Statute § 427.104 prohibit certain collection practices, including:
- Threatening violence or making unlawful threats
- Lying about the amount you owe
- Making false claims about legal action
- Repeatedly contacting you to harass you
If a collector crosses the line, keep records of calls, letters, emails, and messages. You may also be able to dispute the debt.
Protection Against Surprise Medical Bills
The federal No Surprises Act protects many insured patients from certain unexpected out-of-network bills, including emergency care and some services at in-network facilities.
Wisconsin residents can check the Office of the Commissioner of Insurance for more information. These protections have limits, so check whether they apply to your bill.
How to Lower or Resolve Medical Bills
If your medical bills are too high, you may have a few ways to reduce what you owe.
- Check for errors: Ask for an itemized bill and compare it with your insurer’s Explanation of Benefits (EOB). Contact the provider if you find incorrect or duplicate charges.
- Ask for financial help: Many Wisconsin hospitals offer charity care to eligible patients. Contact the billing department to ask about financial assistance, even if your bill has gone to collections.
- Negotiate the balance: Ask about discounts, lower monthly payments, or interest-free payment plans. Get any agreement in writing.
- Dispute unexpected charges: Some uninsured or self-pay patients can challenge bills at least $400 above their good-faith estimate. See the No Surprises Act guidance for details.
- Explore debt relief: If medical bills are part of a larger debt problem, a Wisconsin bankruptcy attorney can explain whether bankruptcy or another option may help.
What If Your Medical Bills Go to Collections?
If you do not pay a medical bill, the provider may send it to a collection agency. The agency may contact you to request payment and may take legal action if the law still allows them to collect the debt.
But a medical bill going to collections does not automatically mean you will be sued or have your wages taken.
If a collector contacts you, check that the debt and amount are correct. Keep copies of any letters, payment records, and messages. If you receive a notice explaining your right to dispute the debt, pay attention to the deadline.
Do not ignore court papers. If a hospital or collector sues you, you may need to respond by a specific date. Missing that deadline can lead to a judgment against you.
A creditor generally must follow legal procedures before garnishing wages. Wisconsin law also provides certain limits and exemptions. If you receive a garnishment notice, get advice about your options as soon as possible.
Can Bankruptcy Help With Medical Debt?
Medical bills are usually unsecured debts. This means they are not tied to property, such as a house or car. You can often discharge qualifying medical debt through bankruptcy, but the right option depends on your finances.
|
Chapter 7
|
Chapter 13
|
| How it works |
Can clear qualifying medical debt without a long-term repayment plan |
Uses a court-approved repayment plan |
| Repayment |
No standard repayment plan |
Usually lasts 3–5 years |
| Eligibility |
Income and other rules apply |
Requires regular income and compliance with debt limits |
| Property |
Some nonexempt property may be sold |
You may be able to keep property while making plan payments |
| Collection actions |
An automatic stay generally pauses many collection actions |
An automatic stay generally pauses many collection actions |
Bankruptcy is not the right answer for everyone. A lawyer can review your income, property, and debts to help you understand the possible benefits and risks.
When Should You Get Legal Help?
Consider speaking with a lawyer if a hospital or collection agency sues you, your wages are being garnished, or a collector is using threats or misleading statements. Legal advice may also help if your medical debt has become part of a larger financial problem.
A Wisconsin bankruptcy lawyer can review the bills, explain your rights, and help you compare your options.
Debt Advisors Law Offices helps Wisconsin residents understand their debt relief options, including bankruptcy, when medical expenses become difficult to manage.
Frequently Asked Questions
Can medical bills be forgiven in Wisconsin?
Yes. Hospital financial assistance may reduce eligible bills, and bankruptcy may clear qualifying medical debt.
Can a Wisconsin hospital sue me for unpaid medical bills?
Yes. A hospital can sue to collect an enforceable debt, but you may have legal defenses.
Can medical debt collectors garnish my wages in Wisconsin?
They may be able to after obtaining a court judgment and following legal procedures. Wisconsin law provides certain limits and exemptions.
Can bankruptcy help me get rid of medical bills?
Yes. Chapter 7 or Chapter 13 may clear qualifying medical debt, depending on your eligibility and circumstances.
Can I apply for hospital financial assistance after a bill goes to collections?
Yes, you may still qualify. Contact the hospital to ask about its eligibility rules and application deadlines.
Get Help With Medical Debt in Wisconsin
Medical bills can make it hard to keep up with rent, groceries, and other everyday expenses. You may have more than one way to deal with the debt, so take time to review your bills and understand your options.
Debt Advisors Law Offices helps Wisconsin residents explore debt relief options when medical expenses become difficult to manage.
Schedule a free consultation to discuss your medical debt and financial situation.